

What costs should I budget for when downsizing?
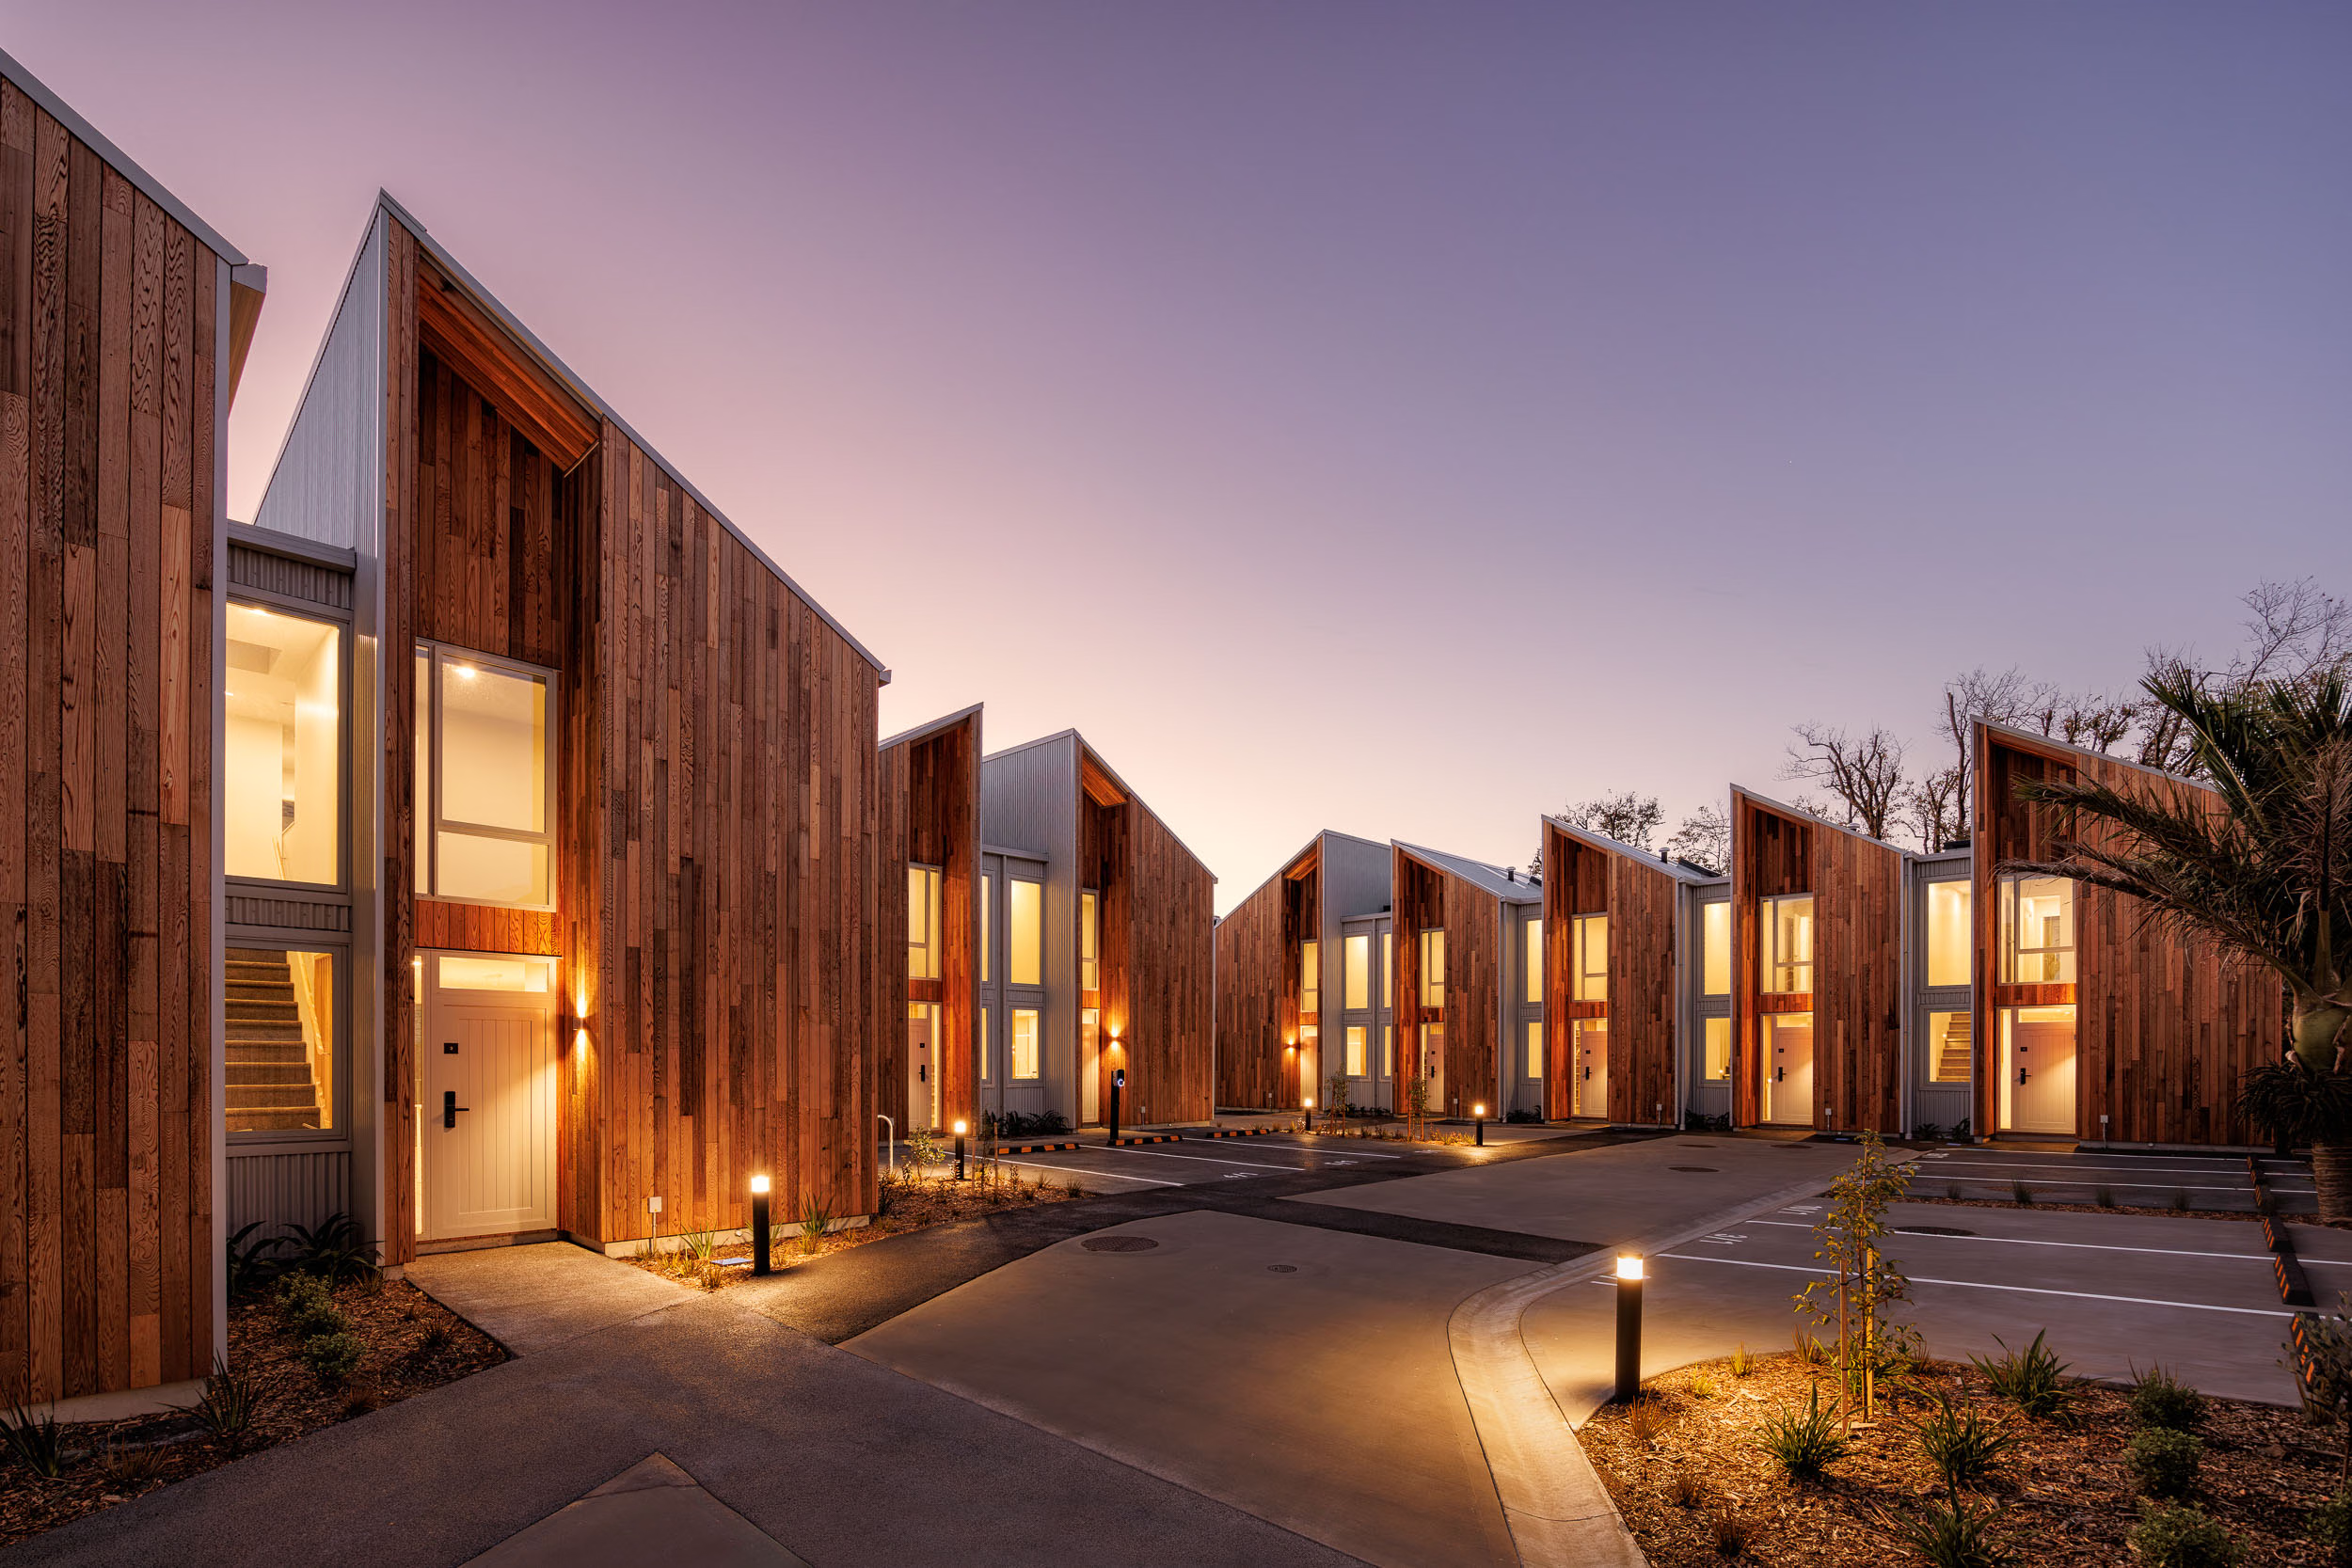
Downsizing in NZ comes with three sets of costs: selling your current home, buying the next one, and moving between the two. The sale and purchase prices do most of the work, but the smaller costs around them decide how much equity you actually free up.
Add them up before you list the house, so nothing arrives as a surprise halfway through a sale. If you’re still deciding whether to move at all, start with how to know it’s time to downsize.
What it costs to sell your home
Agent commission is usually the biggest cost. It’s normally a percentage of the sale price plus GST, and it’s negotiable, so ask two or three agents what they charge.
Legal fees come next, then marketing such as photography and advertising, which some agents list separately. If you’re on a fixed-rate mortgage, check whether paying it off early triggers a break fee. Any tidying, repairs or staging before you list adds to the total.
Your agent and lawyer can give you a figure for your home. Ask for it in writing.
What it costs to buy the next one
You pay legal fees on the purchase too, so expect a second bill from your lawyer. If you’re borrowing, add the bank’s fees and a valuation.
On an older property, a building report and a LIM are standard. A LIM (Land Information Memorandum) is the council’s record of a property. A new build has less hidden in it, but your lawyer should still check the paperwork.
Insurance needs to be in place by the time you take ownership. Ask your insurer when cover has to start.
What it costs to move
Allow for removalists, boxes and any storage. If your sale and purchase dates don’t line up, add short-term storage or somewhere to stay in between.
You may also pay to clear what won’t fit: spare furniture, garden equipment and the contents of the garage. A skip bin or a charity pickup is often cheaper than moving things you don’t want. Allow a little for connecting power and internet and redirecting your mail.
What it costs to live there afterwards
A smaller home should cost less to run, and that saving repeats every year. Rates, insurance and power tend to fall with the size of the home. A new townhouse is insulated to current standards and double glazed, so winter power bills come down too.
A new build also means no renovation budget and nothing significant to replace for years.
Unit title townhouses carry body corporate levies, which cover shared insurance, grounds and building maintenance. Ask to see the budget and the long-term maintenance plan before you buy.
Most of our townhouses are freehold, so there’s no body corporate. Many have a residents’ society that looks after shared areas like the driveway, which usually costs less than a body corporate. We’ve explained the difference in freehold vs unit title.
Putting the numbers together
Start with what your home could sell for and take off the selling costs. That’s what you carry to the next purchase.
Take off the price of the new home and your buying and moving costs, and what’s left is the equity you free up. Keep a buffer for costs that come in higher than expected, and ask your lawyer or an accountant to check the figure before you commit.
A fixed price takes one unknown out
A Faisandier townhouse is sold finished at a fixed price: kitchen in, flooring down, driveway sealed, landscaping done. The price is set before you commit and doesn’t move.
Have a look at our available townhouses, or book a private viewing and talk through timing with our team.
Common questions
What costs should I budget for when downsizing?
On the selling side: agent commission, legal fees and marketing. On the buying side: legal fees, building and LIM reports, and insurance. Then moving costs and any storage. Your lawyer or agent can give you a realistic total.
How much does it cost to sell a house in NZ?
It depends on the value of your home and the agent you choose. The main costs are agent commission (usually a percentage of the sale price plus GST), legal fees and marketing. Ask two or three agents for a written estimate.
Who pays the agent’s commission in NZ?
The seller. When you buy, you don’t pay the agent, though you do pay your own legal fees.
Do I pay legal fees when I sell and buy?
Yes, on both. Many people use the same lawyer for the sale and the purchase, which helps line up the settlement dates. Ask for a quote for each.
Will downsizing save me money?
Often. Downsizing can free up equity, and a smaller home usually costs less to heat, insure and maintain. Your exact figure depends on your sale price, your purchase price and the cost of moving, so ask a lawyer or financial adviser to check the numbers.
Are there ongoing costs in a townhouse?
Yes: rates, insurance and power, as with any home. A unit title townhouse also has body corporate levies. A freehold townhouse has none, though many have a residents’ society fee for shared areas.
Should I get advice before downsizing?
It’s worth speaking to your lawyer, and to an accountant or financial adviser if your situation is complicated. Tax, any mortgage and your other investments can all affect the numbers.
More answers on our frequently asked questions page.
Read more customer stories
Explore more resources
Explore more new and updates

Here's Home: 11 Collingwood Street
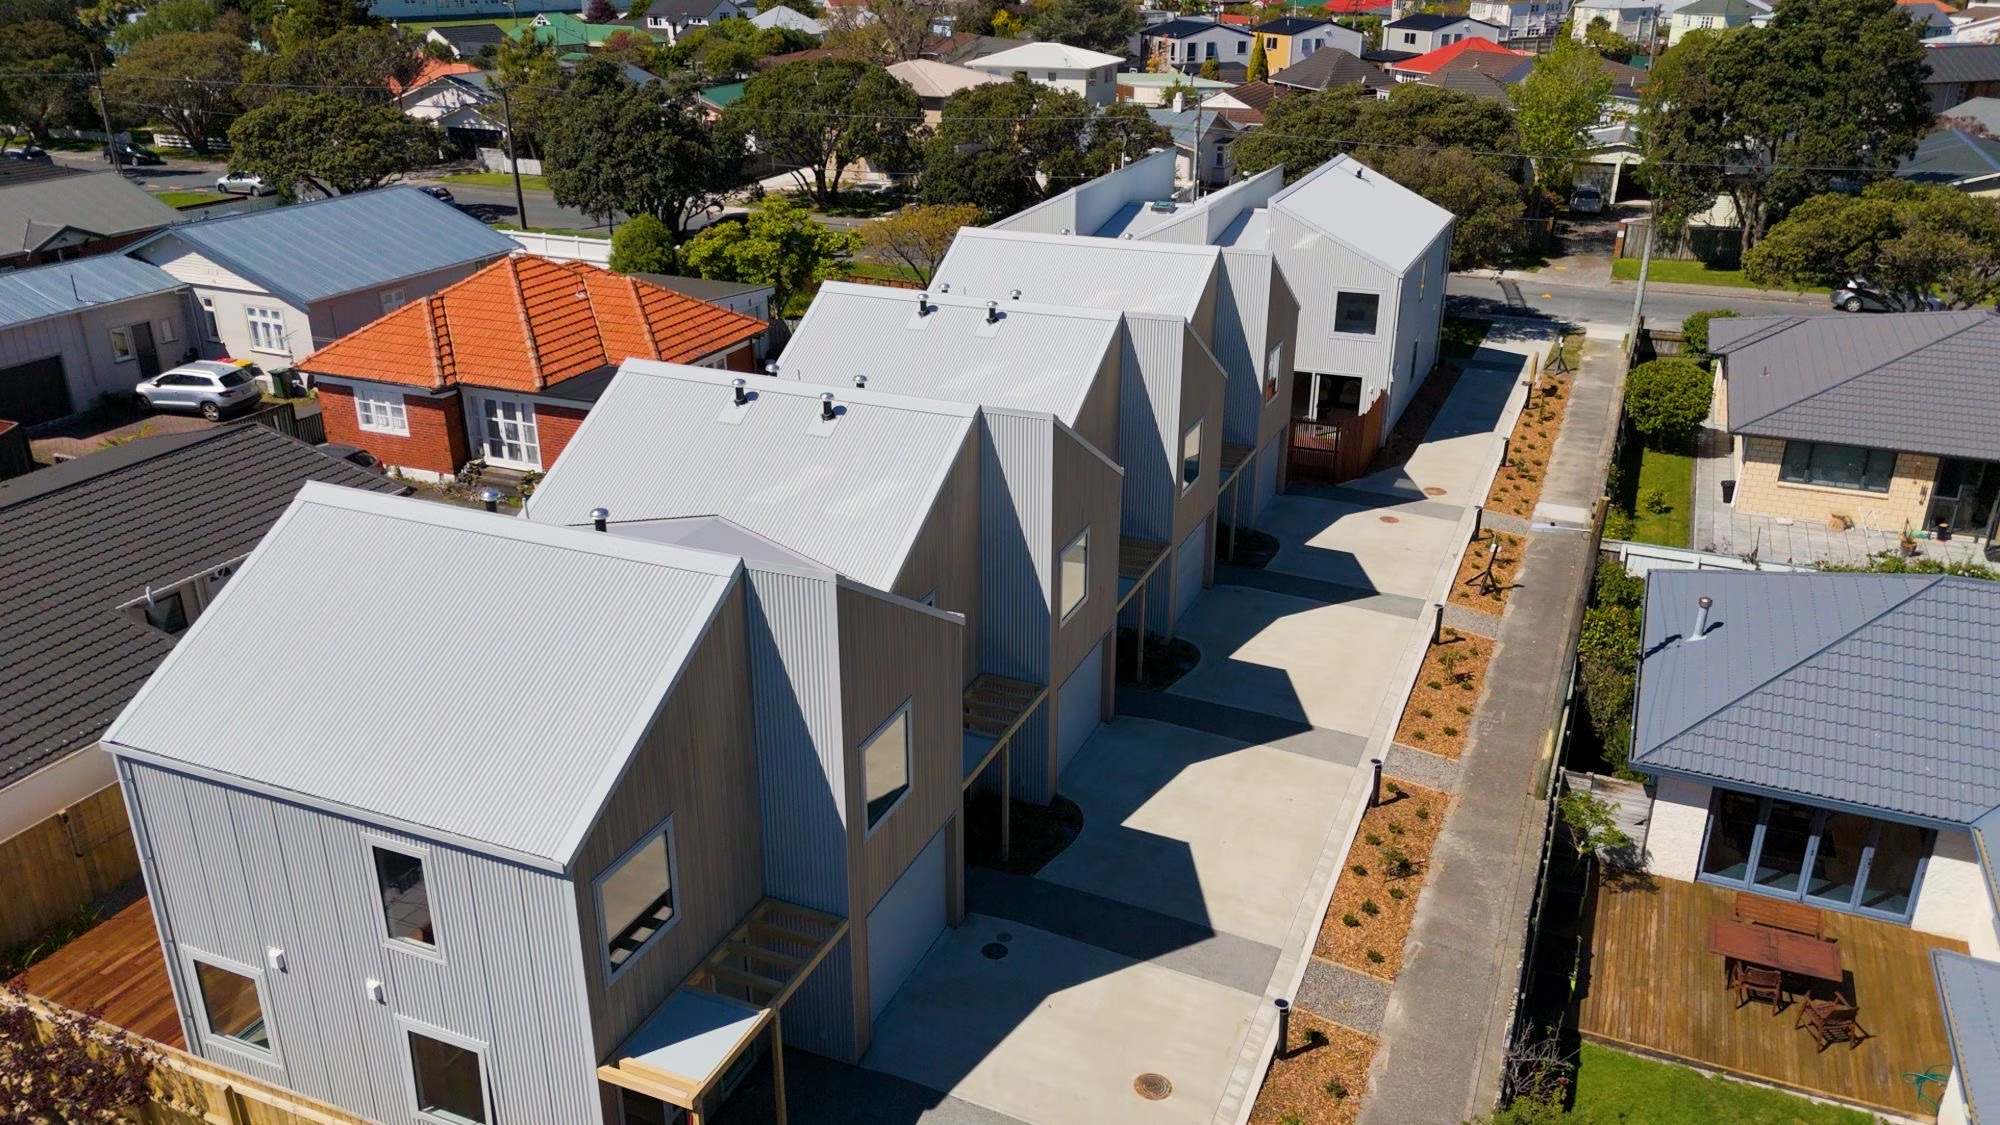
October build update

How do you know it’s time to downsize?
Chat with our team about current availability and start your journey home today.
Contact us